Alternative HomeownershipOptions for Renterswith Unique Qualifications
You can afford the home!
But having trouble getting the mortgage?
If you're self-employed, paid on 1099, earn commissions, own a business, create content for a living, or simply don't fit the traditional mortgage box, you may have another path to a brand-new or newer home.
Answer a few quick questions. We'll review the best next step for your situation.
Check Options Now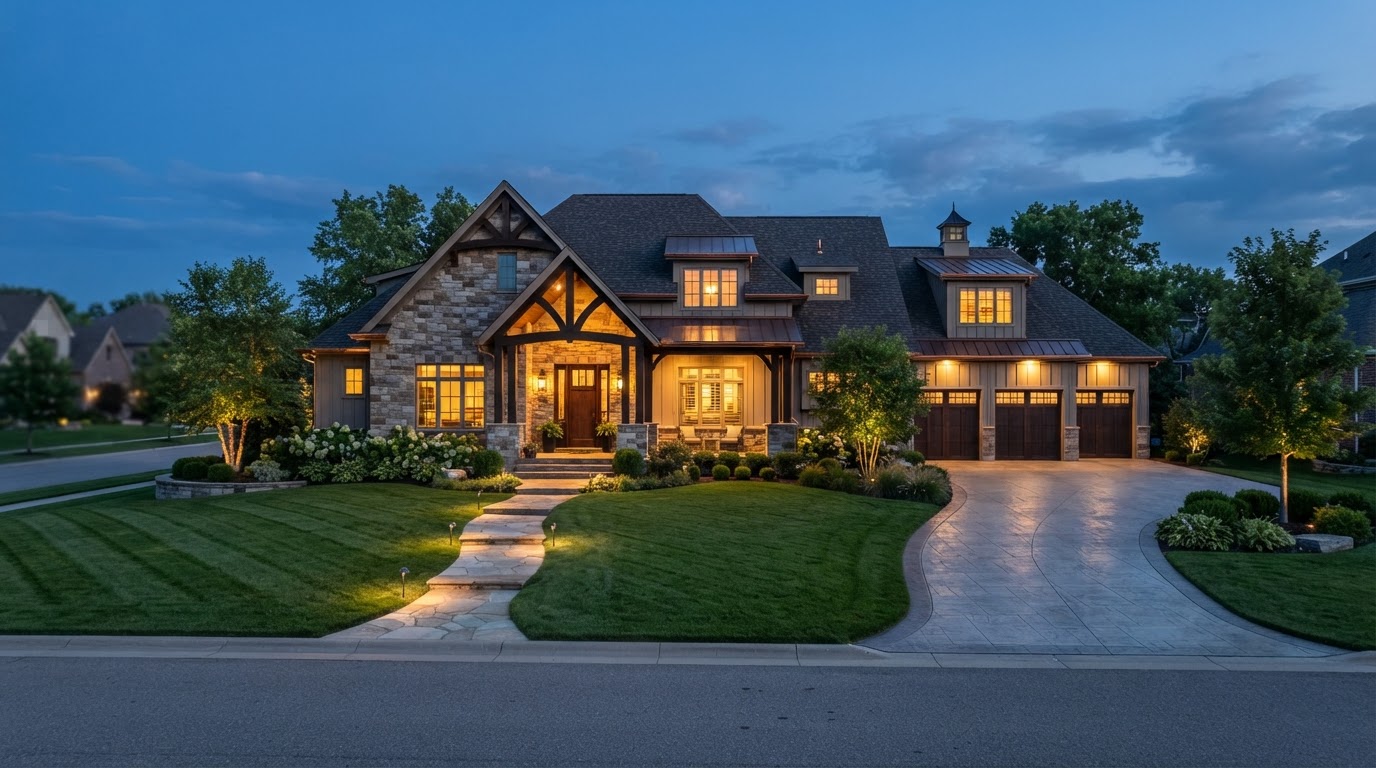
You Pick the Home
Modern layouts · Builder warranties · New finishes
Rent-to-own is the path to the home.It is not the type of home.
This is not old-schoolrent-to-own.
Forget the image of a beat-up house that an owner couldn't sell.
What it is not
This is not about a random owner carrying the financing on a leftover property.
What it actually is
You choose the home based on your approved range. We focus heavily on brand-new and newer homes, including homes where you can be the first person to live there.
That can mean modern layouts, current building standards, builder warranties, new appliances, and a home you would actually want to own long term.
Rent-to-own is the path to the home. It is not the type of home.
Brand-New & Newer
Be the very first occupant or live in a contemporary property built to modern codes.
Builder Warranties
Peace of mind with structural warranties, brand-new appliances, and energy efficiency.
You Choose the House
Pick an eligible home on the open market within your pre-approved range.
Build Equity Rights
Predetermined contract terms that position you for future buyout or refinance.
The kind of homes youcould choose.
You choose the home based on your approved range. These are the types of modern, newer properties our buyers shop — not leftover problem properties.
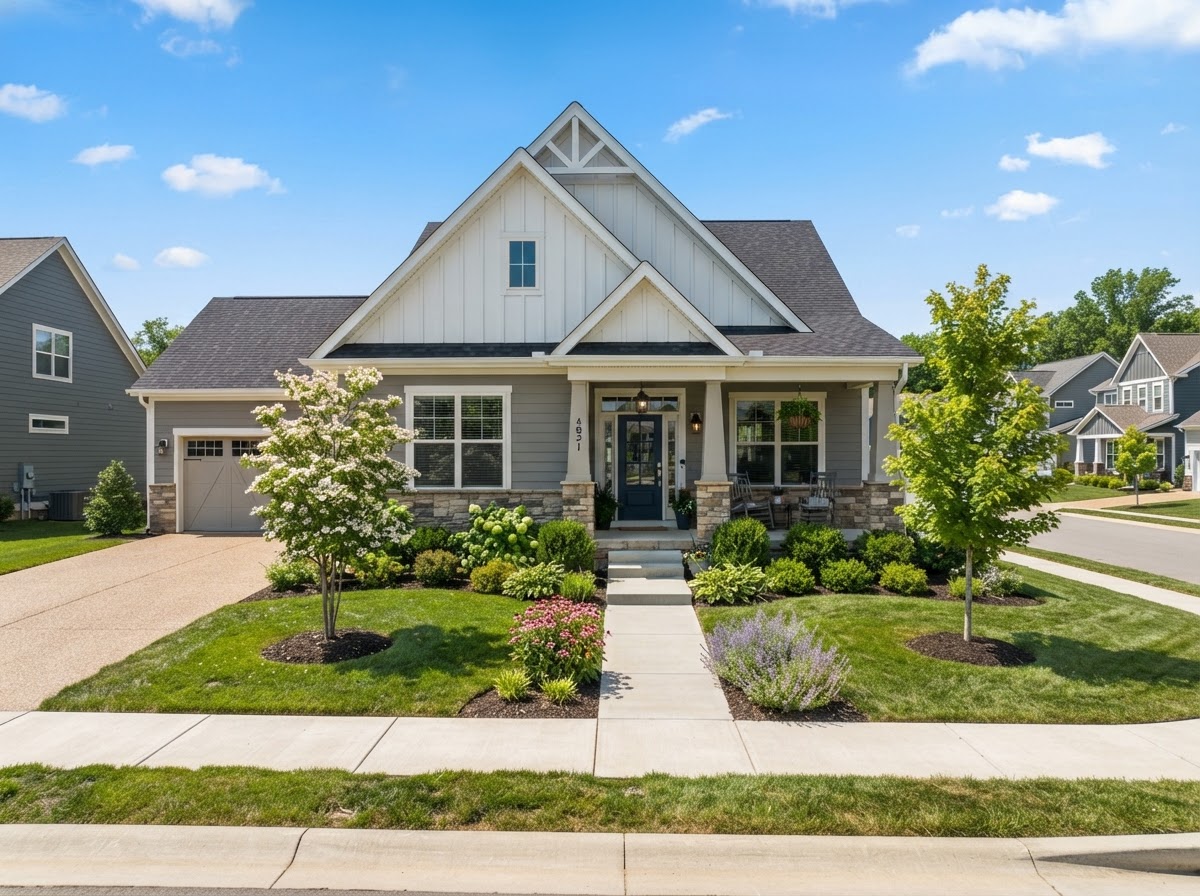
Craftsman — Modern Layout
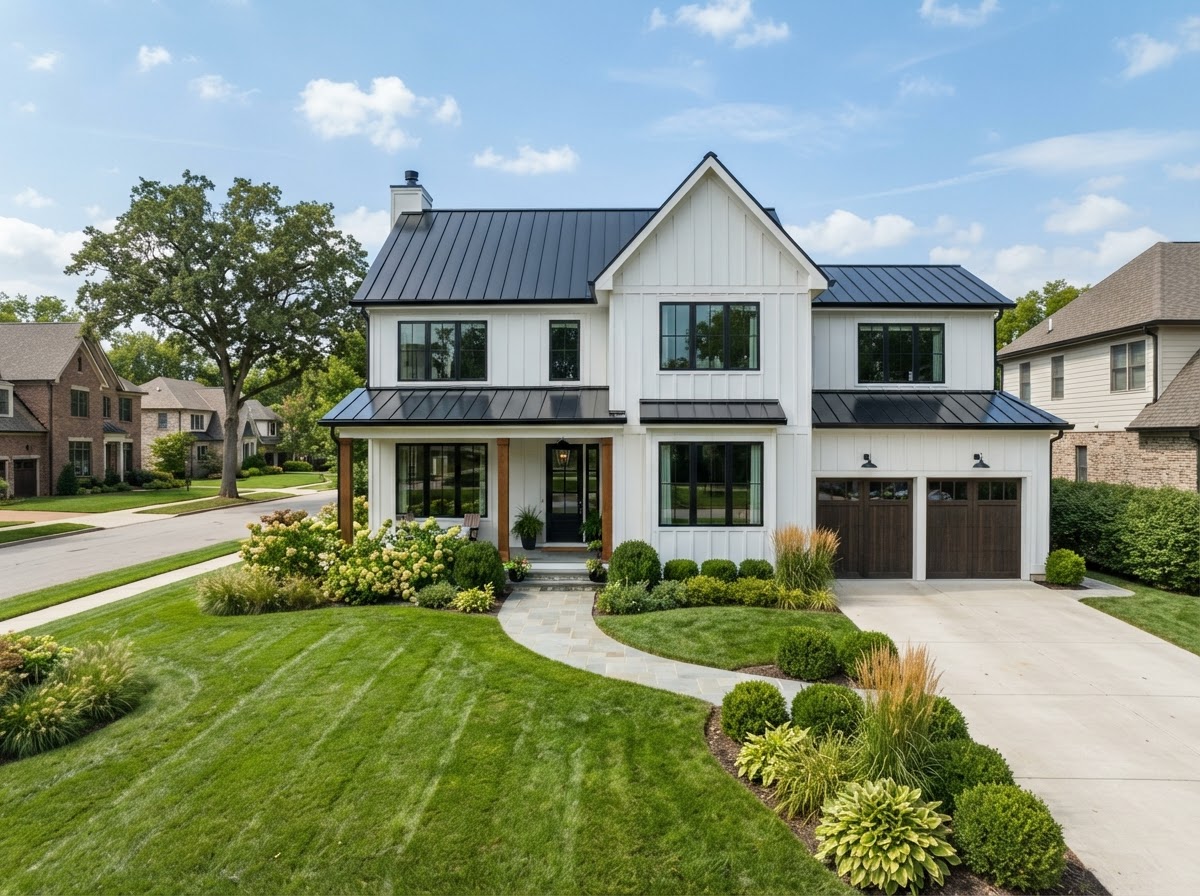
Modern Farmhouse — First Occupant
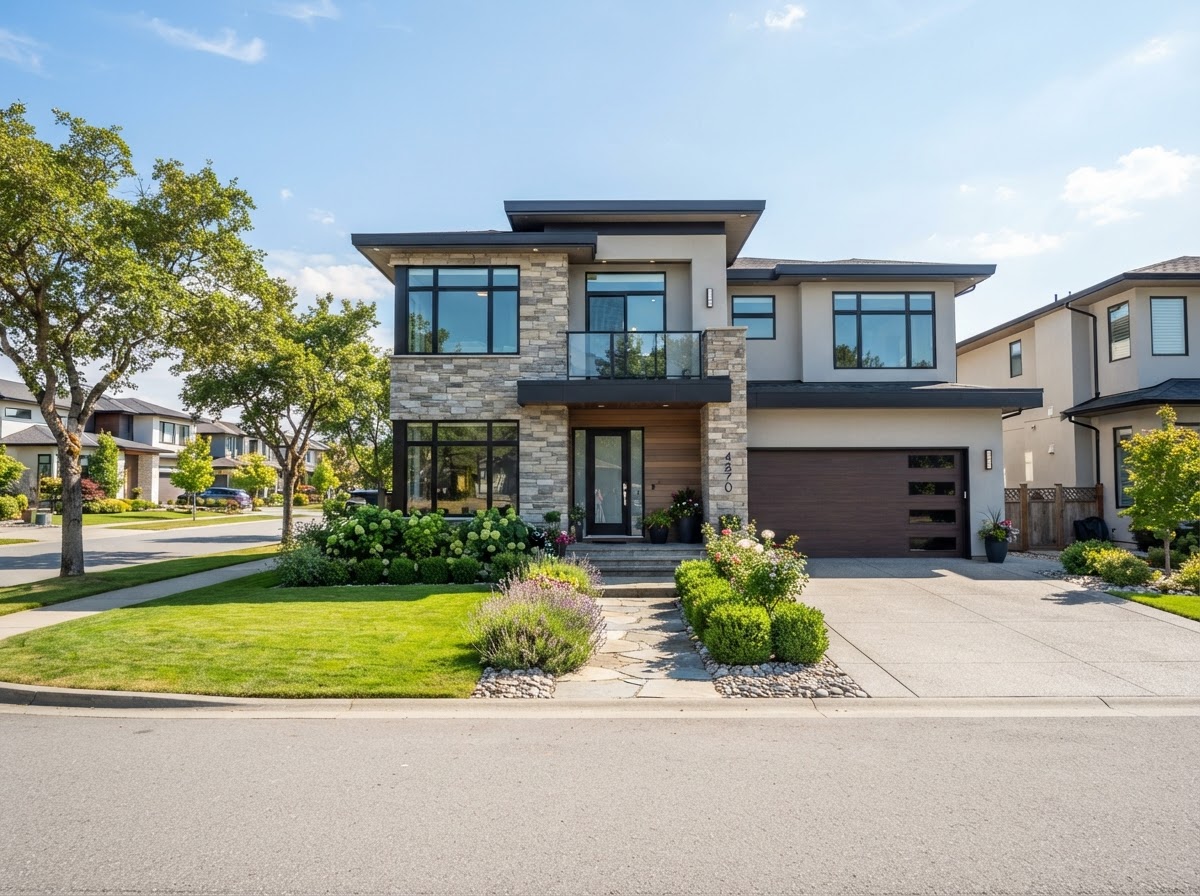
Contemporary Two-Story — Builder Warranty
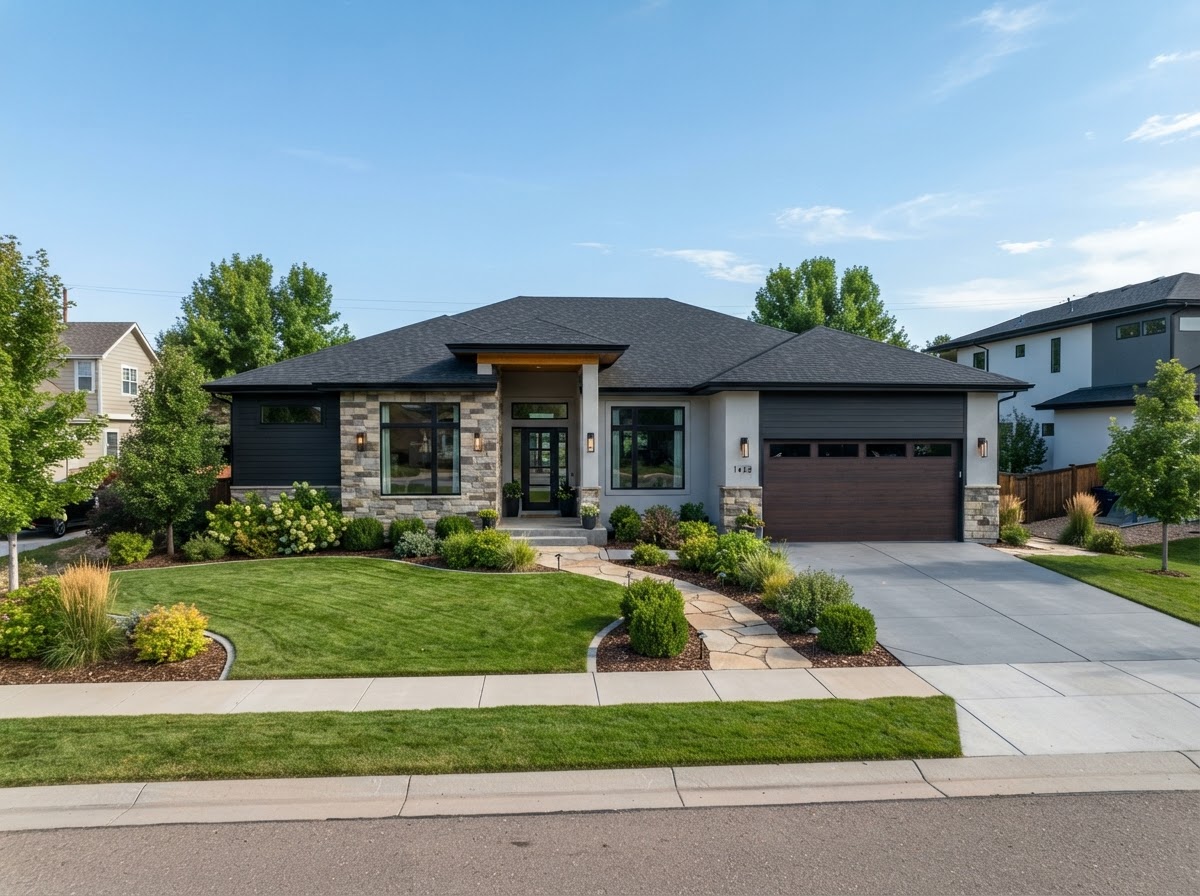
Ranch — Current Building Standards
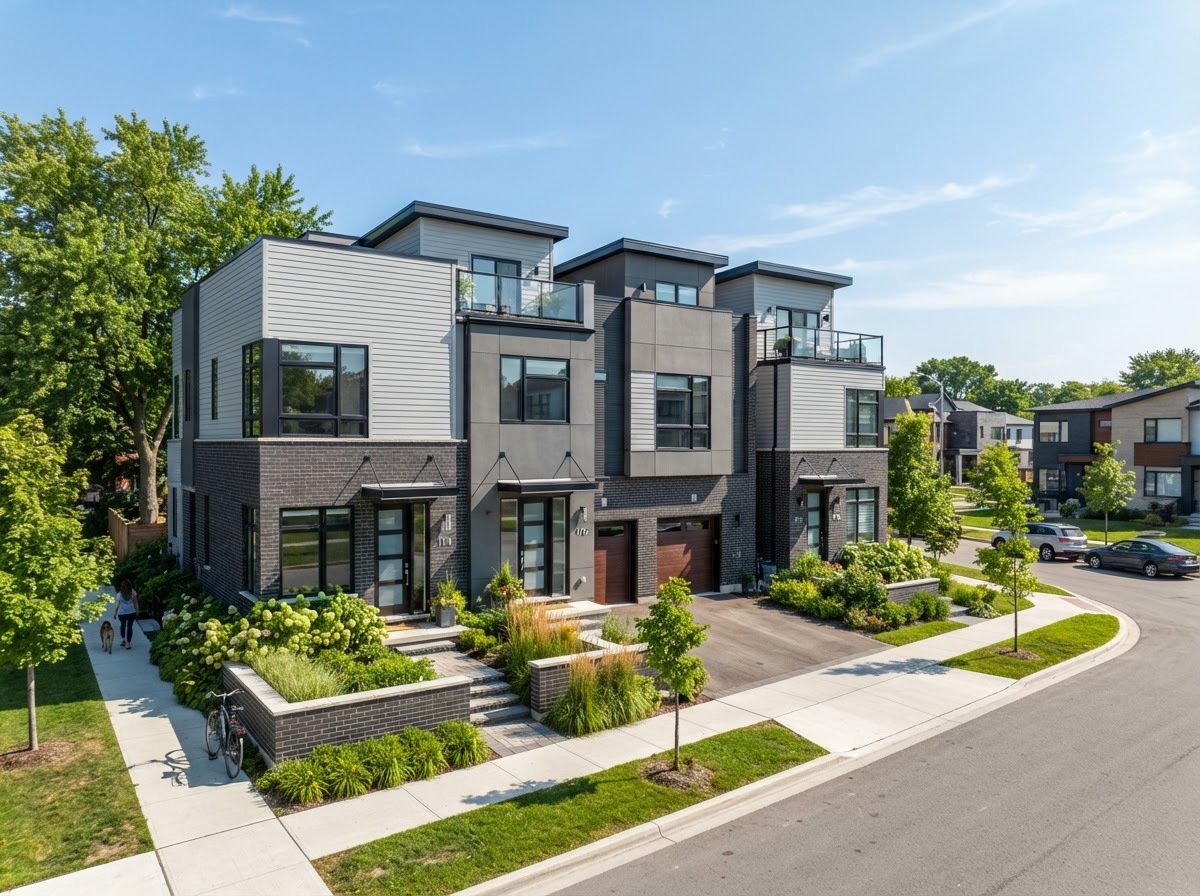
Townhome — New Appliances
Want to see your range?
Check your options to find out which newer homes fit your approved price range.
Check Your OptionsRepresentative newer-home examples for illustration · Actual availability, price ranges, and program terms confirmed after review
Brand-new suburbanhomes you could own.
A closer look at the kind of brand-new construction our buyers shop — modern layouts, current building standards, builder warranties, and homes built to last.
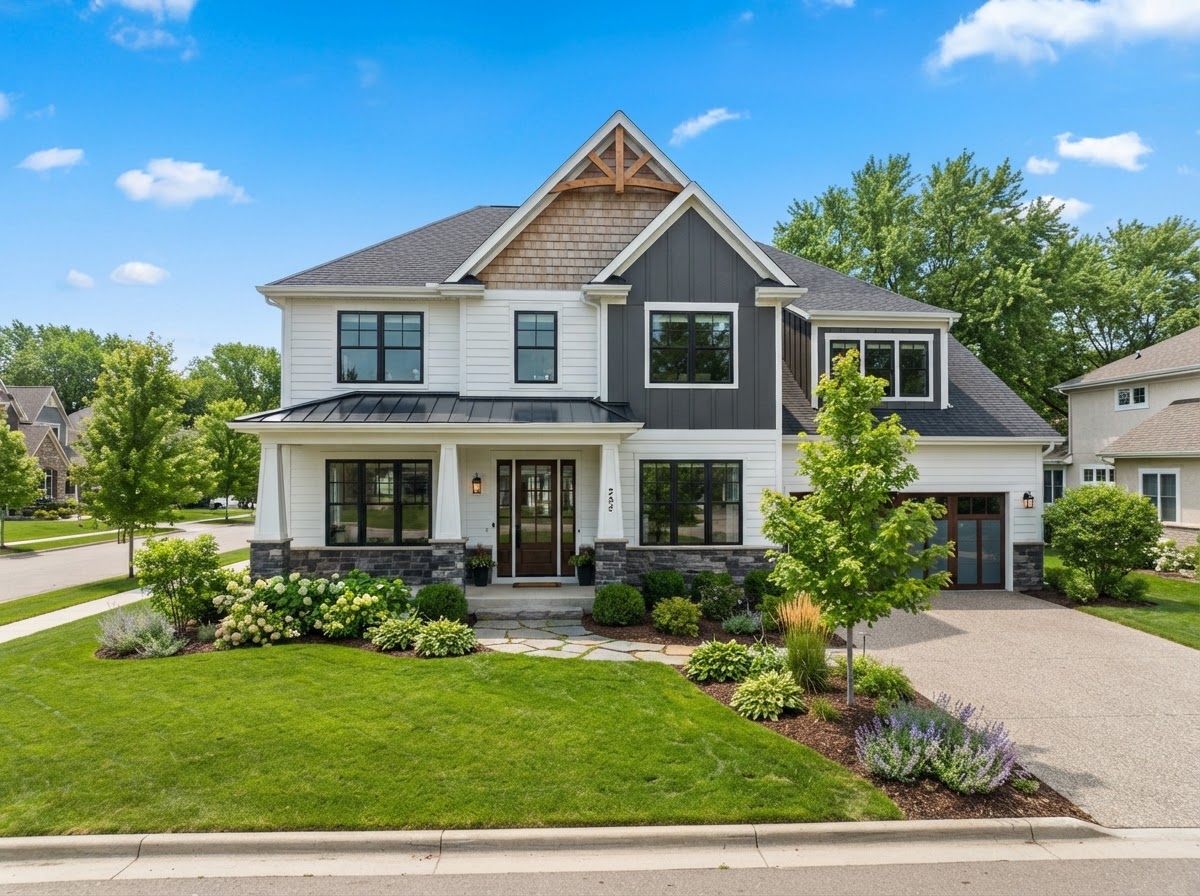
New Construction — Craftsman
Modern layout · Current building standards
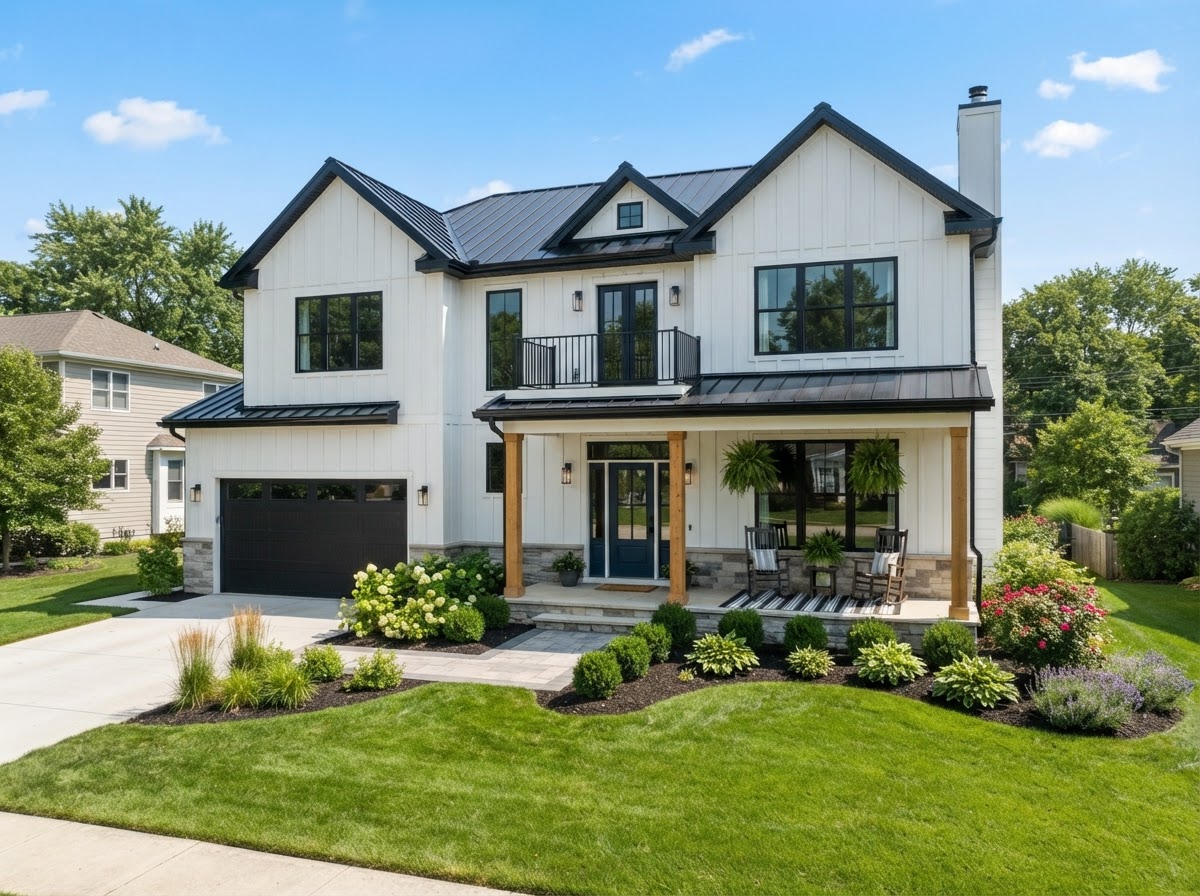
New Construction — Modern Farmhouse
First occupant · Builder warranty
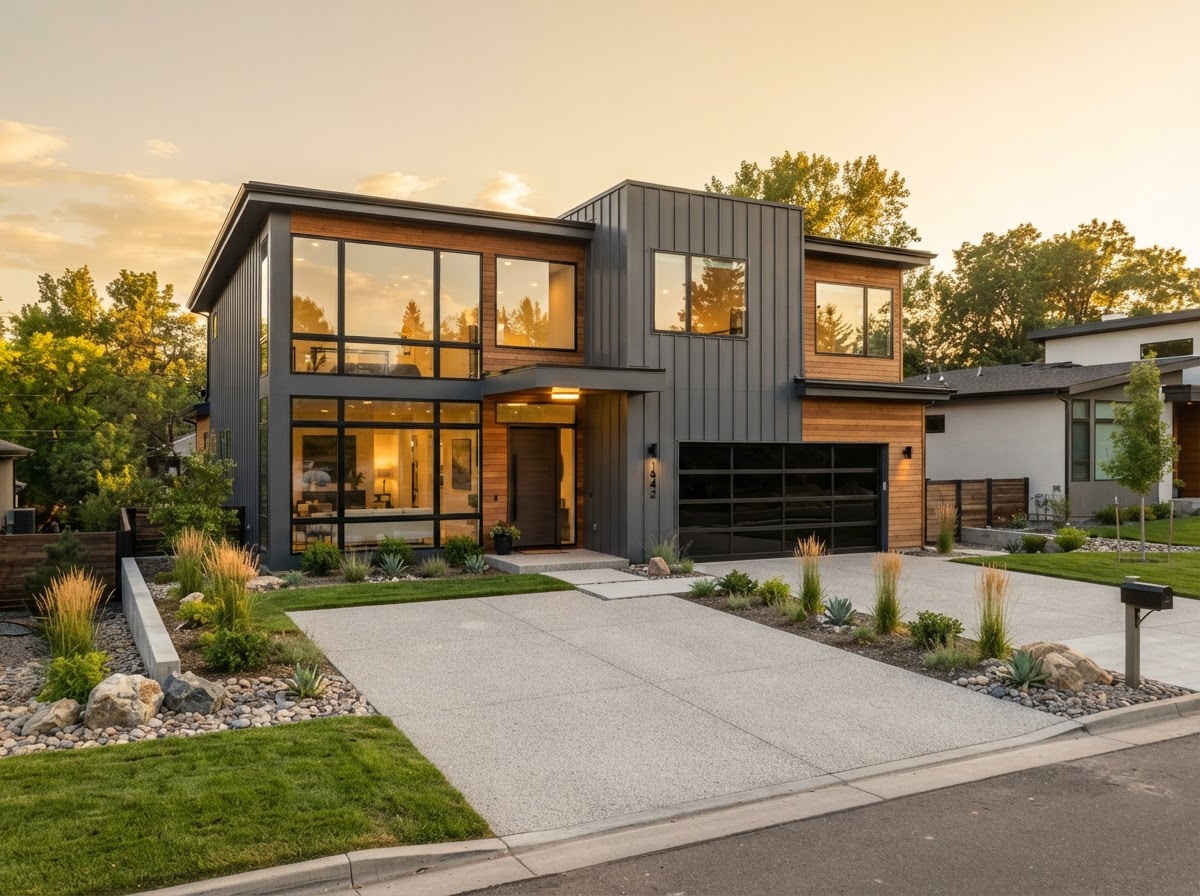
New Construction — Contemporary
New appliances · Energy efficient
Representative new-construction examples for illustration · Actual availability, price ranges, and program terms confirmed after review
Clear & honestqualification fit.
We believe in complete transparency. See who typically excels in this program and who should seek other options.
Who This Is For
Who this may fit.
- Business owners and entrepreneurs
- 1099 workers and independent contractors
- Commission-based professionals
- Content creators and digital creators
- Self-employed buyers with strong bank deposits
- Buyers who can afford the housing payment but do not fit traditional mortgage documentation
- People who were told to wait, come back later, or improve one part of their file before buying
- ITIN buyers who have documentable income and otherwise fit current program guidelines
- Buyers who want a brand-new or newer home, not a leftover problematic property
Who This Is Not For
Probably not the right fit if...
- You have no documentable income
- You have no funds available for the required upfront costs and down payments
- You want to move into a home within the next few days
- You are looking for a no-document, no-underwriting shortcut
- You are looking to only rent and never own
- You expect guaranteed approval
- You are looking specifically for a distressed trailer, severely outdated property, or bargain-basement lease option
- You are unwilling to complete a real underwriting review, including a credit pull
What you'llgenerally need.
Real underwriting. More flexible ways to document your situation.
Documentable income
Recurring deposits or other acceptable documentation may be used. A W-2 is not required for every available path.
A credit review
Current rent-to-own program guidance may consider scores around 560, with lower scores reviewed case by case.
Funds for the transaction
Approximately 4% minimum down for the rent-to-own path, plus applicable closing costs and fees.
Supporting documents
Bank statements and other requested documents may be needed to verify income and deposits.
An eligible home
The property must fit your approved price range and current program requirements.
Enough time to complete the process
Underwriting, home selection, contract review, and closing all take time.
Questions about your bank statements or score?
A W-2 is not mandatory. We review bank statement deposits, 1099s, and alternative documentation daily.
Submit for Quick ReviewHow itworks.
From checking your options to choosing the home.
CHECK YOUR OPTIONS
Complete the short form so we can see which path may fit your income, cash available, credit profile, and target market.
REVIEW THE BEST FINANCING PATH
Rent-to-own may be the right answer. It may also turn out that another mortgage or alternative-documentation option fits you better. The goal is the home, not forcing you into one program.
GET YOUR BUYING RANGE
Once your file is reviewed, you'll know the price range and approximate funds needed before you start seriously shopping.
CHOOSE AN ELIGIBLE HOME
You are not limited to someone's old leftover rent-to-own property. We focus on brand-new and newer homes, and you choose from homes that fit your approved range and program rules.
MOVE IN AND BUILD YOUR OWNERSHIP POSITION
Under the rent-to-own structure, the lender or program entity purchases the home with the agreed program terms. Your price and payment structure are set by the contract, and you begin building equity rights under the program.
REFINANCE, BUY OUT, SELL, OR CONTINUE
When you are ready and qualify, you may refinance or buy out the program after the first year. Depending on the program terms, selling may also be possible. You are not forced into a short one- or two-year deadline with a crazy balloon payment simply because the program started as rent-to-own.
Rent-to-own is not alwaysthe final answer.
Some buyers may fit a different mortgage or alternative-documentation path once their file is reviewed. The goal is to review your options and identify the path that makes the most sense for your situation, not force every buyer into rent-to-own.